Sara Armella

Sara Armella

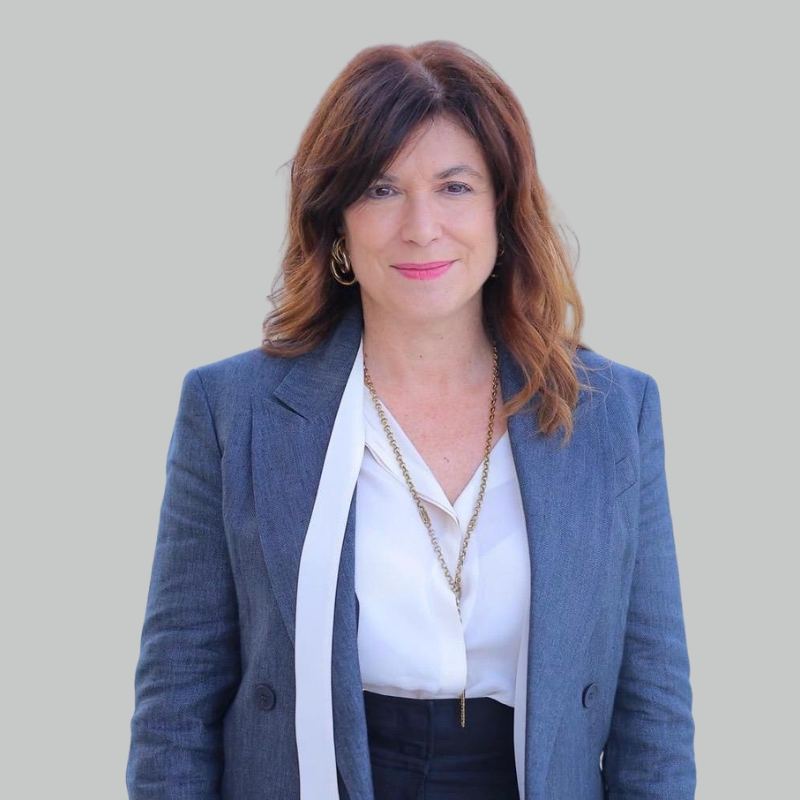
Avvocato e fondatrice dello Studio Armella & Associati, Sara Armella è una delle massime esperte a livello internazionale di diritto doganale

Membro dell’International Customs Law Academy, accademia internazionale che riunisce i cento principali esperti a livello mondiale, dal 2025 è anche Consigliere del Board of Directors di ICLA

Autrice di oltre cento articoli pubblicati su riviste nazionali e internazionali e di quattro monografie, tra cui Diritto doganale dell’Unione europea ed European Union Customs Law, è anche autrice della voce “Tributi doganali” dell’Enciclopedia Treccani online


Presiede la Commissione Dogane di ICC Italia e rappresenta l’Italia presso la Commissione Customs and Trade Facilitation della Camera di Commercio Internazionale di Parigi. È docente di diritto doganale in diversi master post-universitari

Nel 2023 è stata nominata nella Commissione di esperti del Ministero dell’Economia e delle Finanze per la riforma del sistema doganale ed è componente del Gruppo di lavoro Dogane e commercio internazionale di Confindustria e di ICE

È direttore scientifico di Arcom Formazione, scuola di alta formazione per imprese e professionisti

Publications

Monographs

  • Dazi USA. Regole, sfide e opportunità, Lefebvre Giuffrè, Milano, 2025 (coautore Stefano Comisi)
  • Riforma del diritto doganale, Lefebvre Giuffrè, Milano, 2024 (coautrice Antonella Bianchi)
  • European Union Customs Law, Egea Bocconi, Milan, 2017
  • EU Customs Code, BUP, Milan, 2017
  • Customs Law, Egea Bocconi, Milan, 2015

Collaborations on institutional projects

  • European Union Customs Law, in *Derecho aduanero*, Vol. II, edited by German Pardo Carrero, coordinated by S. Ibáñez Marsilla and F.M. Yebra, published by the University of Rosario and Tirant Lo Blanch, Bogotá, 2020;
  • Customs duties, in the Treccani Legal Encyclopedia, Rome, 2015;
  • Tax Profiles and the Customs System, in VAT, Memento Ipsoa-Francis Lefebvre, Ipsoa, Milan, 2011–2020 ed.; The Territoriality of Inheritance and Gift Tax, in The Notary’s Profession and Relations with the Tax Authorities, Altalex, 2014;
  • The Fight Against Tax Evasion, in Tax Legislation in Court Rulings and the New Legislative Session, Cedam, Padua, 2007;
  • Bank investigations, in *Code of Tax Inspections*, Celt, 2005;
  • Customs Audit, in *Code of Tax Inspections*, Celt, 2005;
  • Customs Duties in *International Tax Law*, edited by V. Uckmar, Cedam, Padua, 3rd ed., 2005;
  • Customs Duties. European Union, in *Taxes on International Trade*, edited by V. Uckmar, A. Altamirano, and H. Torres, Buenos Aires, 2003;
  • VAT Territoriality, in *Guide to Reading Tax Case Law*, edited by G. Visentini, Giuffrè, Milan, 2003; VAT Taxable Persons, in *Guide to Reading Tax Case Law*, edited by G. Visentini, Giuffrè, Milan, 2003;
  • The Right to Information in Customs Matters, in *The Right to Request a Ruling: Tax Rulings, EU Customs Information, and the Taxpayer Bill of Rights*, edited by G. Rebora, R. Ruffini, and G. Terracciano, De Agostini Professionale, Rome, 2001;
  • Tax entries from the series *I contratti*, Ipsoa, Milan, 1995–2006;
  • Tax references, in *Contracts 2001* (edited by various authors), edited by V. Cuffaro, Ipsoa, Milan, 2001;
  • Studies on the Constitutions and Tax Legislation of Russia and Luxembourg, in *The Processes of Law Formation*, a strategic and targeted project of the National Research Council (CNR), coordinated by Prof. Piera Filippi;
  • “The Tax Treatment of Indivisible Reserves,” in *The Cooperative Society: Civil and Tax Aspects*, edited by G. Schiano di Pepe and F. Graziano, Cedam, Padua, 1997;
  • "Demergers," in Various Authors, *Corporate Tax Law*, vol. IV of the series *Theoretical and Practical Treatise on Corporations*, edited by G. Schiano di Pepe, Ipsoa, Milan, 1997.

Articles

  • Sanzioni doganali: status quo e criticità insolute, in Corr. trib., 2026;
  • E-commerce e riforma del Codice doganale dell’Unione: profili critici e prospettive di governance, in Corr. trib., 2025;
  • Ancora contrasti sul valore probatorio delle indagini Olaf, in Dir. prat. trib., 2025;
  • CBAM: un nuovo dazio ambientale sulle merci importate, in Corr. trib., 2024;
  • Normativa doganale nazionale più coerente con la disciplina europea, in Corr. trib., 2024;
  • Customs Value in Case Law, in Global Trade and Customs Journal, 2024;
  • Rettifica del valore doganale sulla base di banche dati, in Dir. prat. trib., 2023;
  • Rettifica del valore doganale: utilizzo delle banche dati e rispetto dei criteri contenuti nel CDU, in Corr. trib., 2022;
  • Customs sanctions, the difficult relationship between international harmonization and nation peculiarities, in CASP Journal – Analizy i Studia, 2022;
  • Brexit: What’s Changing in VAT, 2021;
  • For a customs audit, an OLAF report on potential violations is not sufficient, in GT—Journal of Tax Law, 2021;
  • Borders and Protectionism: US Trade Policy and Its Impact on Law, Economy and International Trade, in Global Trade and Customs Journal, 2020;
  • Brexit: Possible Scenarios for Relations Between the European Union and the United Kingdom, in *Corr. trib.*, 2020;
  • Excluding the punitive nature of anti-dumping duties, in *Corr. trib.*, 2020;
  • Royalties are taxed only if there are factual indicators of the licensor’s control, in GT, 2020;
  • VAT Liability for International Services Provided at Ports and Airports, in *VAT*, 2020;
  • The collection of customs duties is unlawful if the Commission annuls the assessment, in L’Iva, 2020;
  • Customs Penalty Regulations: National Law vs. European Principles, in Riv. dir. trib., 2020;
  • The new excise tax regulations, in *L’Iva*, 2020;
  • Customs duties and import VAT: separate tax bases according to the European Court of Justice, in Riv. dir. trib., 2020;
  • The indirect representative is not liable for import VAT, in *Corr. trib.*, 2020;
  • WTO Agreement on Trade Facilitation (TFA): General Rules on the Simplification, Harmonization, and Modernization of Administrative Procedures, in Global Trade and Customs Journal, 2019;
  • Evidence of the Non-Taxability of Intra-Community Transactions: Between Case Law and the 2020 Reform, in GT—Journal of Tax Law, 2019;
  • Anti-dumping duty is unlawful if the right to a fair hearing is violated, in *Corr.trib.*, 2019;
  • The payment notice is valid if the preliminary notice was properly served, in GT-Journal of Tax Jurisprudence, 2019;
  • An improperly claimed and unused VAT credit does not constitute a mere technical violation, in GT—Journal of Tax Jurisprudence, 2019;
  • The pre-assessment hearing is once again under review by the Court of Justice of the European Union, in *Corr.trib.*, 2018;
  • Trademarks and Royalties: Conditions for Customs and VAT Taxability, in *Corr.trib.*, 2018;
  • Determination of Customs Value and the Role of Databases, in *Corr. trib.*, 2018;
  • Tax Cooperation Among EU Countries and Taxpayer Protection, in *Corr. trib.*, 2017;
  • The general charges of the electricity system are classified as indirect taxes, in *Corr. trib.*, 2017;
  • Passive Liability for Customs Liabilities under the New UCC, in *Corr. trib.*, 2017;
  • The regulations on tax monitoring apply only “prospectively.” Limits on the admissibility of the Falciani list, in GT, 2017;
  • Statute of limitations for customs assessments and decriminalization, in *Corr. trib.*, 2016;
  • Is the administrative suspension of customs enforcement subject to a security deposit lawful?, in Corr. trib., 2016;
  • Customs Compliance Tools in Light of the New Union Code, in *Corr. trib.*, 2016;
  • The New Union Customs Code: Changes to the Rules on Customs Value, in *Corr. trib.*, 2016;
  • An OLAF report alone does not justify a customs investigation, in *L’Iva*, 2016;
  • The main changes in the new Union Customs Code, in *Corr. trib.*, 2016;
  • Admissibility of the Vaduz List and Illegally Obtained Evidence in Tax Proceedings, in Corr. trib., 2016;
  • Report of an offense and the statute of limitations for customs assessments, in *Corr. trib.*, 2016;
  • The tax authorities recognize transfer pricing values for customs purposes as well, in *Corr. trib.*, 2016;
  • “Is the ‘esterovestizione’ rule applicable to structures that are not ‘purely artificial’?”, in Corr. trib., 2016;
  • The Supplier’s Liability in Cases of Fraud by a Regular Exporter, in L’Iva, 2016;
  • Tax returns with multiple taxpayers: offsetting is permitted for the calculation of penalties, in L’Iva, 2016;
  • Expanded cases for deferral of the “exit tax,” in *Corr. trib.*, 2015;
  • “Virtual” use of the VAT deposit: the Court of Cassation radically changes its position, in *Corr. trib.*, 2015;
  • “Anti-dumping” duties: cases of refunds, in *Corr. trib.*, 2015;
  • "Use of the Falciani list for tax audits permitted, but it constitutes mere circumstantial evidence," in *Corr. trib.*, 2015;
  • “Cumulative” letters of intent in customs matters, in *Corr. trib.*, 2015;
  • The customs “status” of “containers” is decisive for territoriality, in *Corr. trib.*, 2015;
  • The “first sale price” method: legitimate savings on customs duties, in *Corr. trib.*, 2015;
  • Direct representation at Customs also for the domiciled procedure, in *Corr. trib.*, 2015;
  • "An End to the Controversy Over Subjectivity," in GT, 2015;
  • Import Quotas and Restrictions in Russia, in L’Iva, 2015;
  • Recent applications of the rules on preferential origin, in L’Iva, 2015;
  • Customs declarations: non-adjustable errors, in L’Iva, 2015;
  • Customs Audits and the Preliminary Hearing, in L’Iva, 2015;
  • The Classification Regulations do not apply retroactively, in L’Iva, 2015;
  • VAT deductibility arising from subjectively non-existent invoices if there is good faith, in *L’Iva*, 2015;
  • Customs duties: collection without time limits, but not retroactive, in L’Iva, 2015;
  • No blacklist penalties if the company files an amended return, in Tax News, 2014;
  • Customs: Doubts Regarding the New Rules on Collection During Litigation, in *Corr. trib.*, 2014;
  • "The indirect representative is not liable for import VAT," in *VAT*, 2014;
  • The Effects of the “Equoland” Ruling on the VAT Treatment of “Royalties,” in Corr. trib., 2014;
  • Recent developments in case law regarding double taxation, in L’Iva, 2014;
  • Purchase and sale commissions and the customs value of goods, in *VAT*, 2013;
  • Online Sales: Parties Liable for Non-Payment of Customs Duties, in L’Iva, 2013;
  • Administrative cooperation regarding excise taxes, in *L’Iva*, 2013;
  • The “new” authority of the Customs Service does not have retroactive effect, in L’Iva, 2013;
  • Developments and Issues Regarding the Right to an Excise Tax Credit, in L’Iva, 2013;
  • Interpretive notes on the inward processing regime, in L’Iva, 2013;
  • The Right to an Advance Hearing in Customs Matters, in L’Iva, 2013;
  • The Use of Wiretaps in Tax Proceedings and the Delicate Balance with the Right to a Defense and the Principle of Due Process, in GT, 2013;
  • The Difficulty of Defending Against the Enforceability of Correction Orders Issued by the Customs Agency, in *Corr. trib.*, 2013;
  • The Offense of Smuggling and the Unity of VAT, in *Corr. trib.*, 2013;
  • "Competitive prices and timely deliveries justify blacklisting costs," in *Corr. trib.*, 2013;
  • Effects of the Double Taxation Convention between Italy and San Marino, in *Corr. trib.*, 2013;
  • Alternative export documentation to the SAD and exit records, in *Corr. trib.*, 2013;
  • Recent developments in case law regarding double taxation, in L’Iva, 2012;
  • Measures to protect against dumping practices, in L’Iva, 2012;
  • The criteria for granting AEO status are being tightened: stricter requirements for economic operator status, in L’Iva, 2012;
  • Territorial jurisdiction of the Customs Agency and the illegality of assessment notices, in L’Iva, 2012;
  • Violations of the “Made in Italy” label and new powers for Chambers of Commerce, in L’Iva, 2012;
  • Can the regular exchange of information between states remedy the original illegality of the Falciani list? In *Corr. trib.*, 2012;
  • Shipping Costs: Customs Regulations and VAT, in *VAT*, 2012;
  • Measures to protect against “dumping” practices, in L’Iva, 2012;
  • The criteria for granting AEO status are being tightened: more vehicles required for economic operator status, in L’Iva, 2012;
  • “Exit Tax”: Taxation of unrealized capital gains suspended until actual realization, in *Corr. trib.*, 2012;
  • Taxation of dividends based on the recipient’s actual residence, in *Corr. trib.*, 2012;
  • The extension of the time limits for tax assessments does not apply if no criminal complaint has been filed, in *Corr. trib.*, 2012;
  • Strengthening of Customs Investigations and a New Penalty System, in L’Iva, 2012.
  • “Waived” tax years for VAT purposes, extension of time limits, and statute-barred offenses, in *Corr. trib.*, 2012;
  • “Exit tax”: taxation of unrealized capital gains suspended until actual realization, in *Corr. trib.*, 2012;
  • Uncertainty regarding the criminal relevance of the abuse of rights and the doubling of time limits, in *Corr. trib.*, 2012;
  • The customs value of goods in intra-group transactions, in *L’Iva*, 2012;
  • Critical Aspects of the Abuse of Rights in Indirect Taxation, in *Corr. trib.*, 2012;
  • Failure to submit a security deposit under the VAT group scheme cannot be penalized in the same way as tax evasion, in GT, 2011;
  • Place of taxable transactions: EU definitions require a revision of domestic law, in *Corr. trib.*, 2011;
  • For cooperatives with a predominantly mutualist structure: “2010 tax audits” without the use of sector-specific studies, in *Corr. trib.*, 2011;
  • The concept of residence for VAT purposes does not correspond to that used for direct tax purposes, in *Corr. trib.*, 2011;
  • New rules regarding the determination of the customs origin of goods, in L’Iva, 2011;
  • Taxpayer Protection: Advance Rulings and Binding Interpretations, in L’Iva, 2011;
  • Tax Warehouses for VAT Purposes: Unresolved Issues, in *L’Iva*, 2011;
  • New guidelines on the provisional suspension of customs assessments, in L’Iva, 2011;
  • VAT Requirements: Unresolved Issues, in *L’Iva*, 2011;
  • Place of taxable transactions: EU definitions require a revision of domestic law, in *Corr. trib.*, 2011;
  • New VAT territoriality and rules on non-taxability, in L’Iva, 2011;
  • The concept of residence for VAT purposes does not correspond to that used for direct tax purposes, in *Corr. trib.*, 2011;
  • For cooperatives with a predominantly mutualist structure: “2010 tax audits” without the use of sector-specific studies, in *Corr. trib.*, 2011;
  • Customs clarifications on the new export rules, in L’Iva, 2011;
  • “Emissions trading” transactions: legal classification affects territoriality, in Corr. trib., 2011;
  • The Supreme Court broadens the scope of the offense of import VAT evasion, in GT, 2011;
  • Importer Liability in Cases of Inaccurate Certificates of Origin, in L’Iva, 2011;
  • Place of taxable transactions: the definitions require a revision of domestic law, in *Corr. trib.*, 2011;
  • Liability Profiles of Customs Brokers, in L’Iva, 2011;
  • Failure to file a security deposit in a group VAT return cannot be penalized in the same way as tax evasion, in GT, 2011;
  • Customs assessment notices issued without a preliminary hearing are invalid, in L’Iva, 2011;
  • The statute of limitations for customs assessments, in L’Iva, 2010;
  • The customs value of goods and royalties, in *VAT*, 2010;
  • “Is Import VAT Distinct and Independent from Domestic VAT?”, in Corr. trib., 2010;
  • "Are sector-specific studies applicable to cooperatives?", in *Corr. trib.*, 2010;
  • In the customs sector, a restrictive ruling by the Court of Cassation, in GT, 2010;
  • The Statute of Limitations on Customs Liabilities and the Need to Harmonize EU Regulations with National Laws, in GT, 2009;
  • Good faith of the importer and liability for invalid certificates, in GT, 2007;
  • Second Budget Law: Establishment of the Financial Transactions Registry, in *Dir. prat. trib.*, 2006;
  • Reflections on the composition with creditors and tax assessment reform, in *Corr.trib.*, 2003;
  • "A customs authority’s error precludes the recovery of duties," in Dir.prat.trib.int., 2003;
  • Proof of export. Important clarifications from the Customs Agency, in *Corr.trib.*, 2003;
  • The Concept of Residence in EU and Domestic Law, in *Corr.trib.*, 2002;
  • "Proof of Export," in *L’Iva*, 2002;
  • Problematic aspects regarding the application of customs penalty regulations, in *Corr.trib.*, 2001;
  • The VAT regime for port and airport services, in *Corr.trib.*, 2001;
  • Interpretive criteria regarding the territoriality of VAT on the provision of services, in *Corr.trib.*, 2001;
  • Notes on the Concept of Customs Duties in Domestic and International Law, in Riv.dir.trib., 2001;
  • Brief notes on the compatibility of indirect taxes with EU regulations on VAT and excise taxes and on the recovery of overpaid taxes, in Riv.dir.trib., 2000;
  • The VAT regime for e-commerce, in Dir.prat.trib., 1999;
  • The concept of economic activity for VAT purposes, in Dir.prat.trib., 1999;
  • The VAT Treatment of Leasing Transactions Involving Means of Transport Within the European Union, in Riv.dir.trib., 1998;
  • The VAT Treatment of Arbitration Services, in Dir.prat.trib., 1998;
  • The VAT regime for travel agencies, in *Riv. dir. trib.*, 1997;
  • The VAT regime for the transport of goods and passengers in international and intra-Community contexts, in Dir. prat. trib., 1997;
  • According to the Court of Justice, even a copy of the purchase invoice is sufficient to justify a VAT deduction, in *Riv. dir. trib.*, 1997;
  • Comments on taxes having equivalent effect, the prohibition of discrimination, and the recovery of overpayments, in *Riv. dir. trib.*, 1996;
  • Property Tax in Cases of Surface Rights, in *Dir. prat. trib.*, 1996;
  • The European Court of Justice rules that default interest on VAT due upon final importation is unjustified, in Dir. prat. trib., 1996;
  • The tax treatment of the provision of services passes the test of the European Court of Justice, in Dir.prat.trib., 1996;
  • The Reserves of Cooperative Societies and Article 12 of Law No. 904 of 1977, in *Dir. prat. trib.*, 1996;
  • The ransom paid for the release of the kidnapped “manager” is not tax-deductible, in Dir. prat.trib., 1995;
  • Retroactive Taxation of Expropriation Compensation: Issues of Interpretation and Doubts Regarding Constitutional Legitimacy, in Dir. prat. trib., 1995;
  • Case law, administrative, and doctrinal guidelines on insurance tax, in Dir. prat. trib., 1994;
  • Exceeding the customs value limit: what are the penalties?, in Dir. prat. trib., 1994;
  • On the deduction of the improvement contribution from the Invim, in *Dir. prat. trib.*, 1993.

Information

  • Name:

    Sara Armella
  • Role:

    Managing partner
  • Qualification:

    Managing partner
  • Skills:

    Tax Law
  • Languages:

    English, French
logo
logo

International Legal and Tax Advisory Services

Contact us

Operational Offices

15/6 Via Torino – 20123 Milan
4/2 Piazza De Ferrari – 16121 Genoa